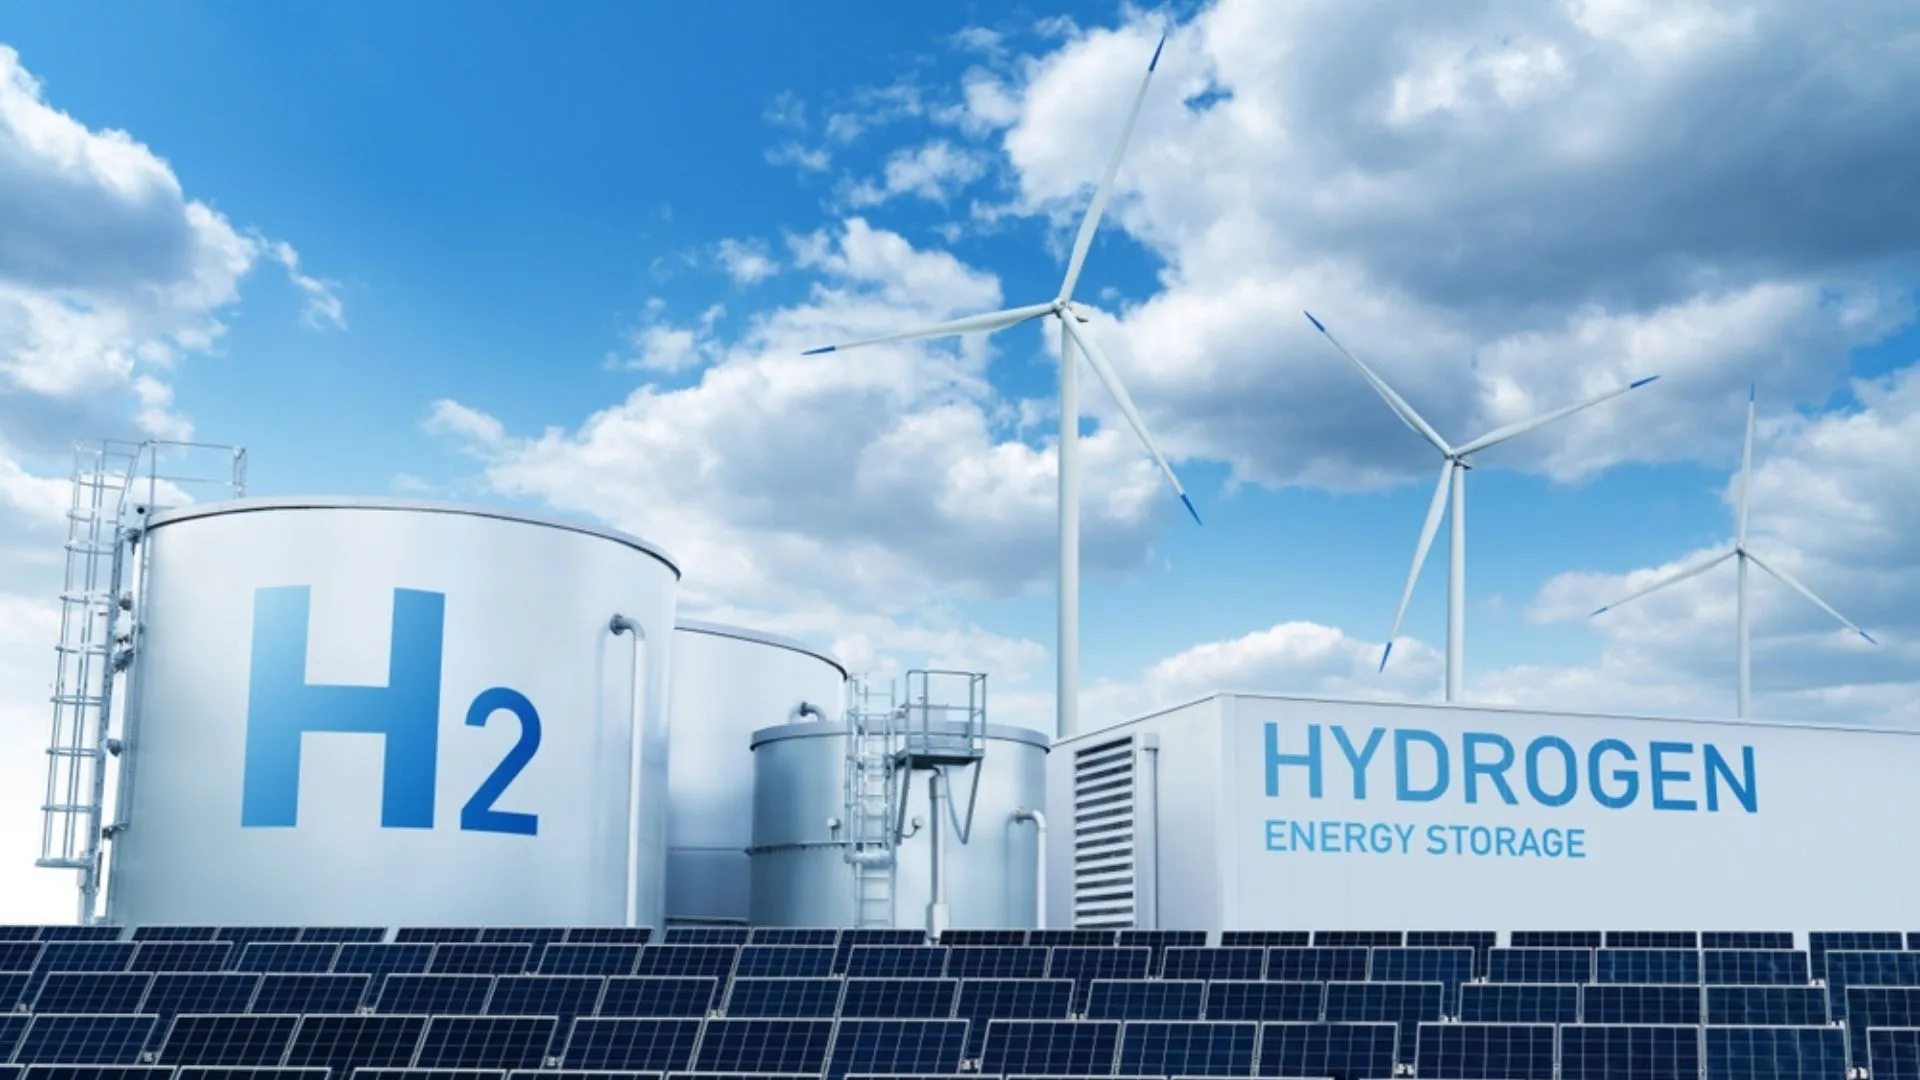
The committed investment supports more than 570 clean hydrogen projects and a global production capacity of 6.9 million tons per year.
Global investment committed to projects of Clean hydrogen exceeded $130.000 million according to data from the Hydrogen Council’s Global Hydrogen Compass 2026, this capital is linked to more than 570 projects that, together, represent a projected production capacity of 6.9 million tons per year.
Furthermore, with nearly 90% of these projects already under construction or in operation, the global capacity for clean hydrogen production currently in operation nearly doubled during the last year, and the report anticipates similar growth in 2027, as new facilities currently under development come online.
The study was prepared by the Hydrogen Council together with McKinsey & Company and brings together input from around 70 CEOs from different parts of the world.
China accounts for more than half of the renewable hydrogen capacity
By region, China accounts for more than half of the world’s committed capacity of renewable hydrogen the country also accounts for nearly 90% of the new operational capacity added globally since 2025.
Europe ranks second among the main markets, the region leads in number of projects and has recorded a 35% increase in investment since 2025. For its part, the United States maintains a relevant position in the low-emissions segment, the country concentrates approximately 75% of the global committed capacity of low-carbon hydrogen and ammonia.
These figures reflect that the market is progressing differently in each region, China accounts for a large part of the growth in renewable hydrogen, the United States accounts for a large part of the low-carbon projects, and Europe maintains a high rate of investment and development.
Hydrogen is gaining importance in the energy strategy
Furthermore, the Hydrogen Council links the growth in investment to a shift in the priorities of governments and industries. Security of supply, economic resilience, and industrial competitiveness are gaining increasing importance alongside decarbonization goals.
He clean hydrogen it can help meet part of the energy demand in sectors where direct electrification is more complex. It can also complement the deployment of renewable energy within systems that require other alternatives for certain industrial processes.
In this scenario, the sector is beginning to move beyond a stage focused mainly on announcements and planning to advance towards a phase in which more and more projects are under construction or are already operational.
The policies could trigger 11 million tons of demand
However, supply growth also requires sufficient demand to sustain new investment, current policies could mobilize around 11 million tons of annual demand for clean hydrogen by 2030.
Of that volume, approximately 6 million tons per year are already backed by approved and implemented policies. The remaining 5 million tons will depend on governments fulfilling existing commitments and developing mechanisms capable of providing clearer signals to buyers.
These tools include incentives, mandates, and carbon pricing mechanisms, at the same time, the industry faces the challenge of reducing production costs and developing the infrastructure needed to connect new capacity to consumers.
Thus, the volume of committed capital confirms that the clean hydrogen market already has a considerable portfolio of projects. Its next stage will depend on how much of that capacity actually becomes operational and whether it manages to find economically sustainable demand.
Source: EnergyNow
Photo: Shutterstock